The Student Loan Borrower's Playbook for Repayment and Forgiveness
From original sourcesGeneral information from the sources it names, not personalized advice.
Built from the creator's sources. How Capxule uses AI
About this Capsule
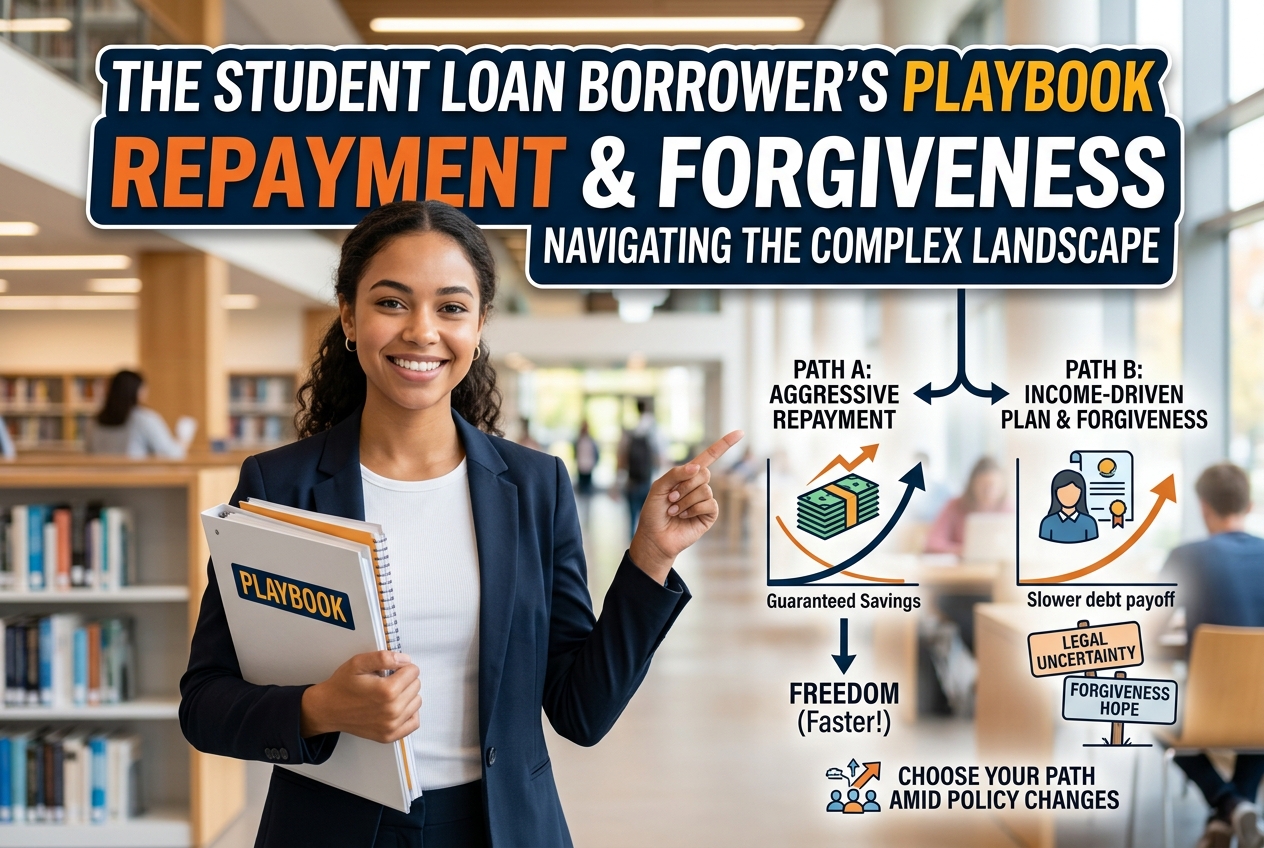
Student loan borrowers face a complex landscape where aggressive repayment, income-driven plans, and hopes for forgiveness collide. Legal challenges have halted popular forgiveness programs, forcing borrowers to weigh guaranteed savings from paying down debt against uncertain relief options. Understanding how these strategies differ in risk, cost, and timeline helps borrowers choose the best path amid ongoing policy changes.
4 smart strategies for student loan repayment
Evaluating student loan repayment choices
Navigating uncertain student loan repayment landscape
Try asking: “Are IDR applications currently being processed?”
Conservative, risk-averse personal finance approach
Student loan strategy comparison and review
Questions this capsule answers
Tap any question to get it answered inside the capsule, free.
Generic AI vs AI with This Capsule
Preview“What should student loan borrowers actually focus on when deciding between paying off debt aggressively and pursuing forgiveness programs?”
Generic AI
“Student loan borrowers should focus less on “paying debt feels good” vs. “forgiveness sounds free” and more on which path minimizes risk-adjusted lifetime cost while supporting their career and financial stability.
1. Start with loan type: federal vs. private
This is the first filter.
Federal loans
Federal loans may qualify for income-driven repayment, Public Service Loan Forgiveness, deferment/forbearance protections, and other relief programs.
If you have federal loans, do not refinance into private loans unless you are confident you do not need or want those protections.
Private loans
Private loans generally do not qualify for federal forgiveness programs.
If your loans are private, the decision is usually more straightforward: pay them down aggressively if the interest rate is high, while still maintaining an emergency fund and retirement basics.
2. Compare total...”
This Capsule
“Focus on the bet you’re actually making, not just the interest rate. PSLF is a 10-year employment bet: “Can I realistically stay in qualifying public/nonprofit work long enough?” Aggressive payoff is a 5–7-year cash-flow bet: “Can I consistently throw large payments at the debt without wrecking housing, retirement, family, or emergency savings?” Block 45 minutes and run exactly two scenarios side by side: one PSLF/forgiveness path and one aggressive payoff path.
1. Compare total cost, not vibes
For the forgiveness path, estimate:
- Your income for each of the next 10 years
- Your available income-driven repayment plan
- Your estimated monthly payment each year
- Annual payment = monthly payment × 12
- Total PSLF cost = sum of 10 years of payments
- Remaining balance forgiven if you complete PSLF
For the aggressive payoff path, estimate:
- Current...”
The Student Loan Borrower's Playbook for Repayment and Forgiveness
Capxule Finance
View profile
Related in Finance
Morocco Expert-Comptable Qualifying Exam
Become a chartered accountant in Morocco: the full road to the Diplome National d'Expert-Comptable, from the ISCAE entrance exam through the three certificates, the three-year stage and the memoire, to OEC membership under Law 15-89, with exam-style practice.
Pass the CFA Level I
A handcrafted AI study companion for the CFA Institute Level I exam: the full ten topic curriculum, exam format, ethics, and test day rules, taught topic by topic with original practice drills.

An Heir's Guide to Clearing an Inherited House Sale
Inheriting a house doesn’t mean you can sell it right away. Local legal hurdles like probate, title searches, and lien clearances create distinct pitfalls that can delay or block a sale. Understanding whether you’re stuck in court approval, tangled in ownership disputes, or facing hidden debts helps you decide the right path to clear the way for a smooth sale.

An Adult Child's Handbook for Aging Parent Care and Finances
Discussing money and care with aging parents before a crisis helps avoid confusion and conflict later. The steps differ on how to organize important documents, set ethical boundaries, and prepare legally and financially for future needs. You’ll learn how to gather and secure critical information, plan for long-term care costs, and ensure smooth access to accounts and decisions when the time comes.